Best Countries for
Low-Tax Living
in 2027
Bulgaria, Greece, Malta, Panama, Singapore, UAE, Uruguay and other jurisdictions offer different approaches to attracting HNWIs and companies. This guide examines the most tax-efficient countries for 2027 — and the residency questions globally mobile individuals should ask before making a move.
Introduction
Strategic Relocation Planning
For high-net-worth individuals, entrepreneurs and internationally mobile families, choosing where to live is increasingly a strategic financial decision. Taxation, political stability, asset protection, inheritance planning and access to international markets all influence where wealthy individuals choose to establish their primary residence.
As governments compete to attract international capital and talent, some jurisdictions offer favorable tax treatment to new residents, including flat-tax arrangements, exemptions on certain foreign-source income and territorial tax systems. Others offer established legal frameworks and lifestyle advantages that appeal to families seeking a long-term international base.
There is no universally best country for tax residency. The right choice depends on the nature and location of an individual's income, the composition of their assets, their nationality, family circumstances and willingness to relocate.
What Makes a Country Attractive?
Key Evaluation Criteria
A favorable personal income tax rate is only one part of the equation. Wealthy individuals should consider several factors before choosing a new tax residence:
- —Foreign-source income: How does the country tax dividends, interest, capital gains, rental income and business profits generated abroad?
- —Wealth and inheritance taxation: Are foreign assets, worldwide wealth, gifts or inheritances subject to local taxation?
- —Tax residency requirements: How many days must an individual spend in the country, and what other economic or personal connections are required?
- —Immigration options: Is residency available through investment, property ownership, employment, business activity or independent means?
- —International tax treaties: Does the country have a network of double taxation agreements?
- —Lifestyle and security: Does it offer political stability, quality healthcare, good education, reliable infrastructure and access to international business centers?
- —Long-term flexibility: Can family members obtain residency, and does the country offer a pathway to permanent residence or citizenship?
Obtaining a residence permit does not automatically establish tax residency. Equally, acquiring tax residency in another country does not automatically terminate tax obligations in the country an individual is leaving.
Best Countries for Tax Residency in 2027
Country-by-Country Analysis
Malta
European Residency and Remittance-Based Taxation
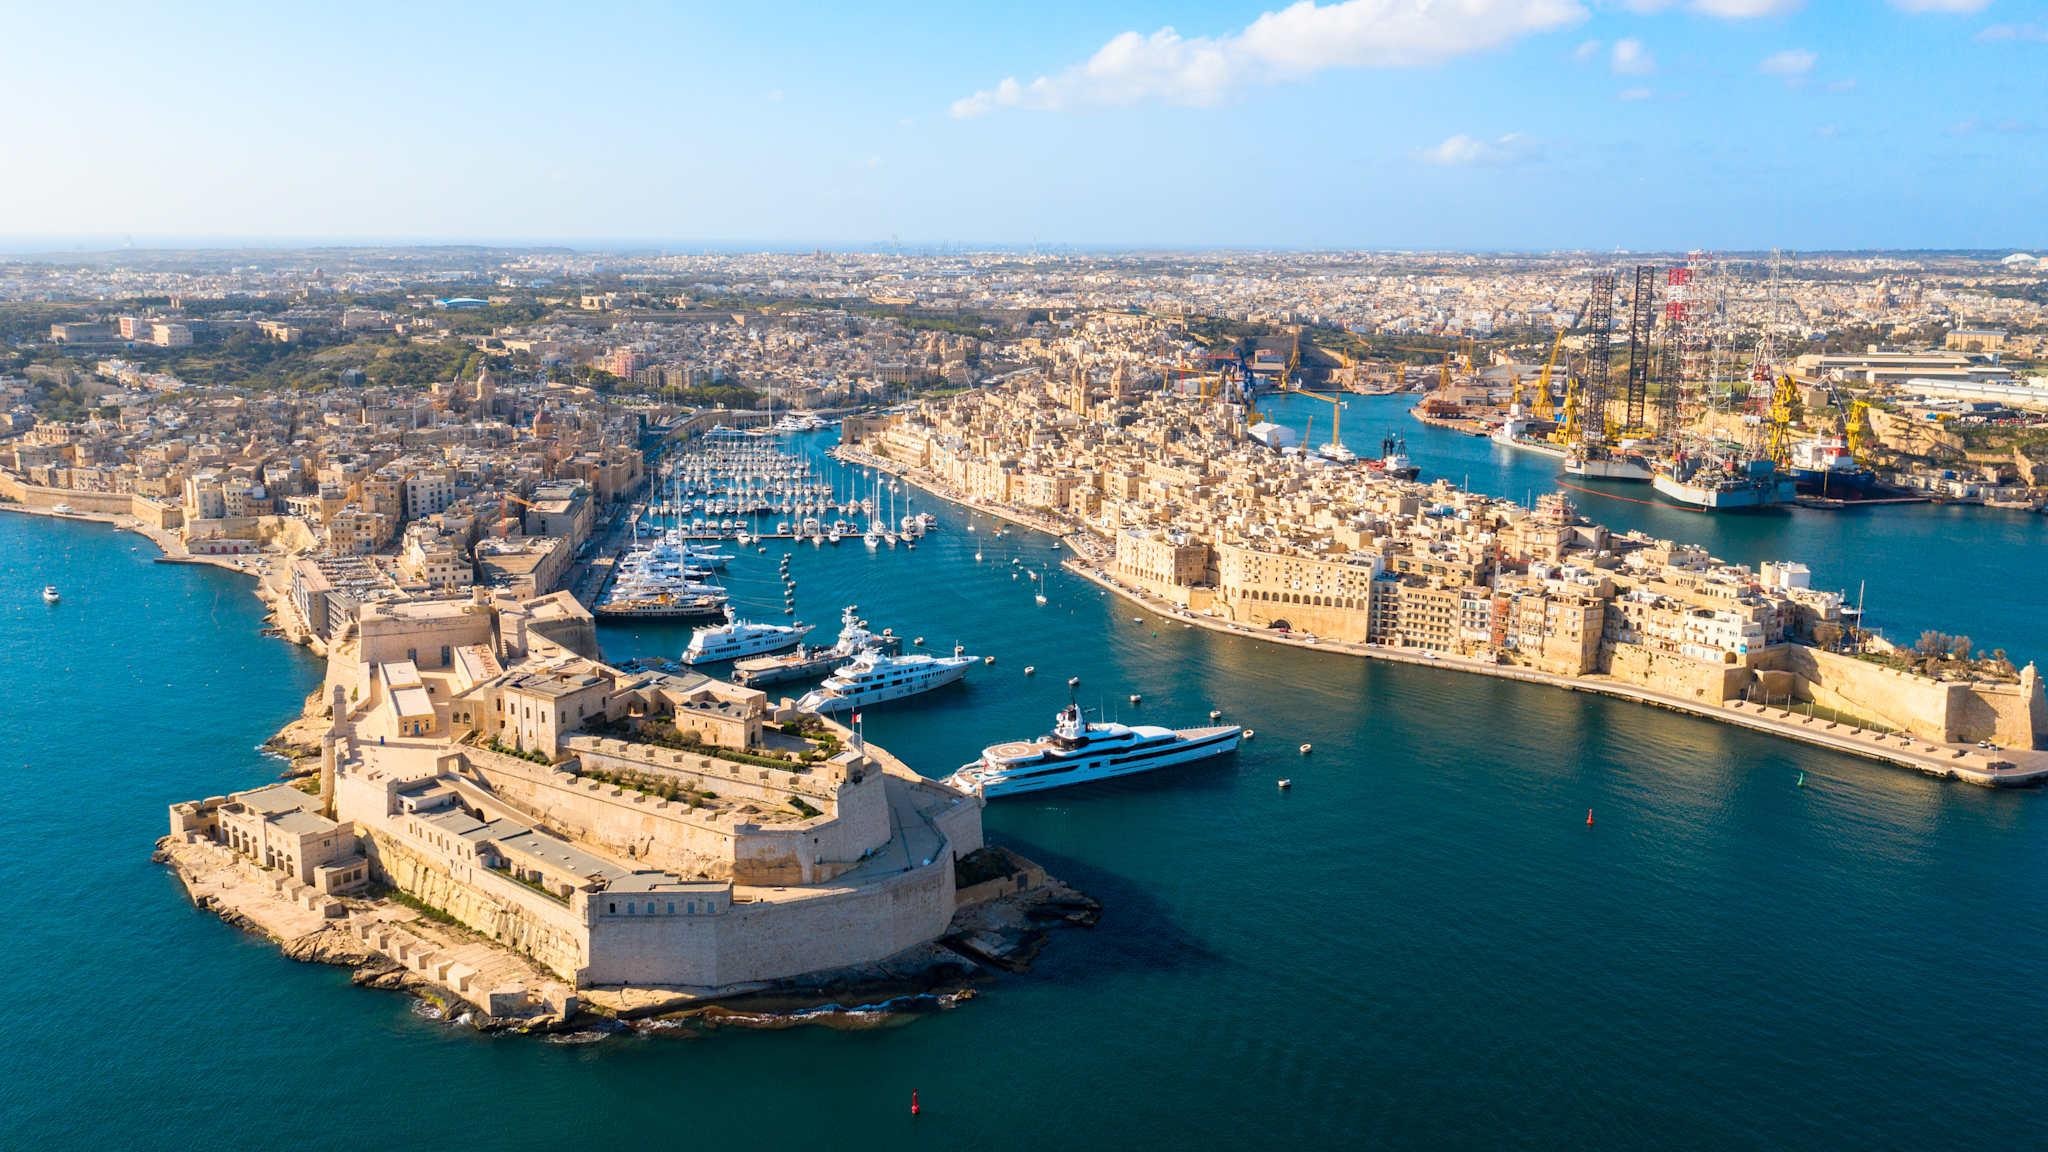
Malta remains an interesting option for internationally mobile individuals who want an English-speaking European base, access to the European Union and a favorable framework for certain foreign-source income.
Under Malta's special residence tax arrangements, qualifying non-domiciled individuals can generally benefit from a 15% tax rate on qualifying foreign-source income remitted to Malta. Foreign-source income not remitted to Malta is generally outside the Maltese tax charge under the relevant program, while Maltese-source income is generally taxed at 35%.
Malta's new Individual Tax Program consolidates several existing special tax residence arrangements into a single framework. For applicants under Global Resident Status and EU, EEA and Swiss Resident Status, the minimum annual tax liability increases to €35,000 from 1 January 2027. The new rules also introduce higher qualifying property requirements, including a minimum purchase value of €700,000 or annual rent of €14,000.
Existing beneficiaries and qualifying applications submitted by 31 December 2026 benefit from transitional arrangements.
Why consider Malta?
- ✓English is an official language.
- ✓EU membership and Schengen access.
- ✓Established international financial and professional services sector.
- ✓Remittance-based tax treatment for qualifying individuals.
- ✓A practical European base for internationally connected families.
Malta is particularly worth considering for individuals whose foreign-source income structure makes the remittance basis attractive and who are comfortable with the new minimum tax and property requirements.
Explore Malta residency options →Cyprus
60-Day Tax Residency and Non-Dom Advantages
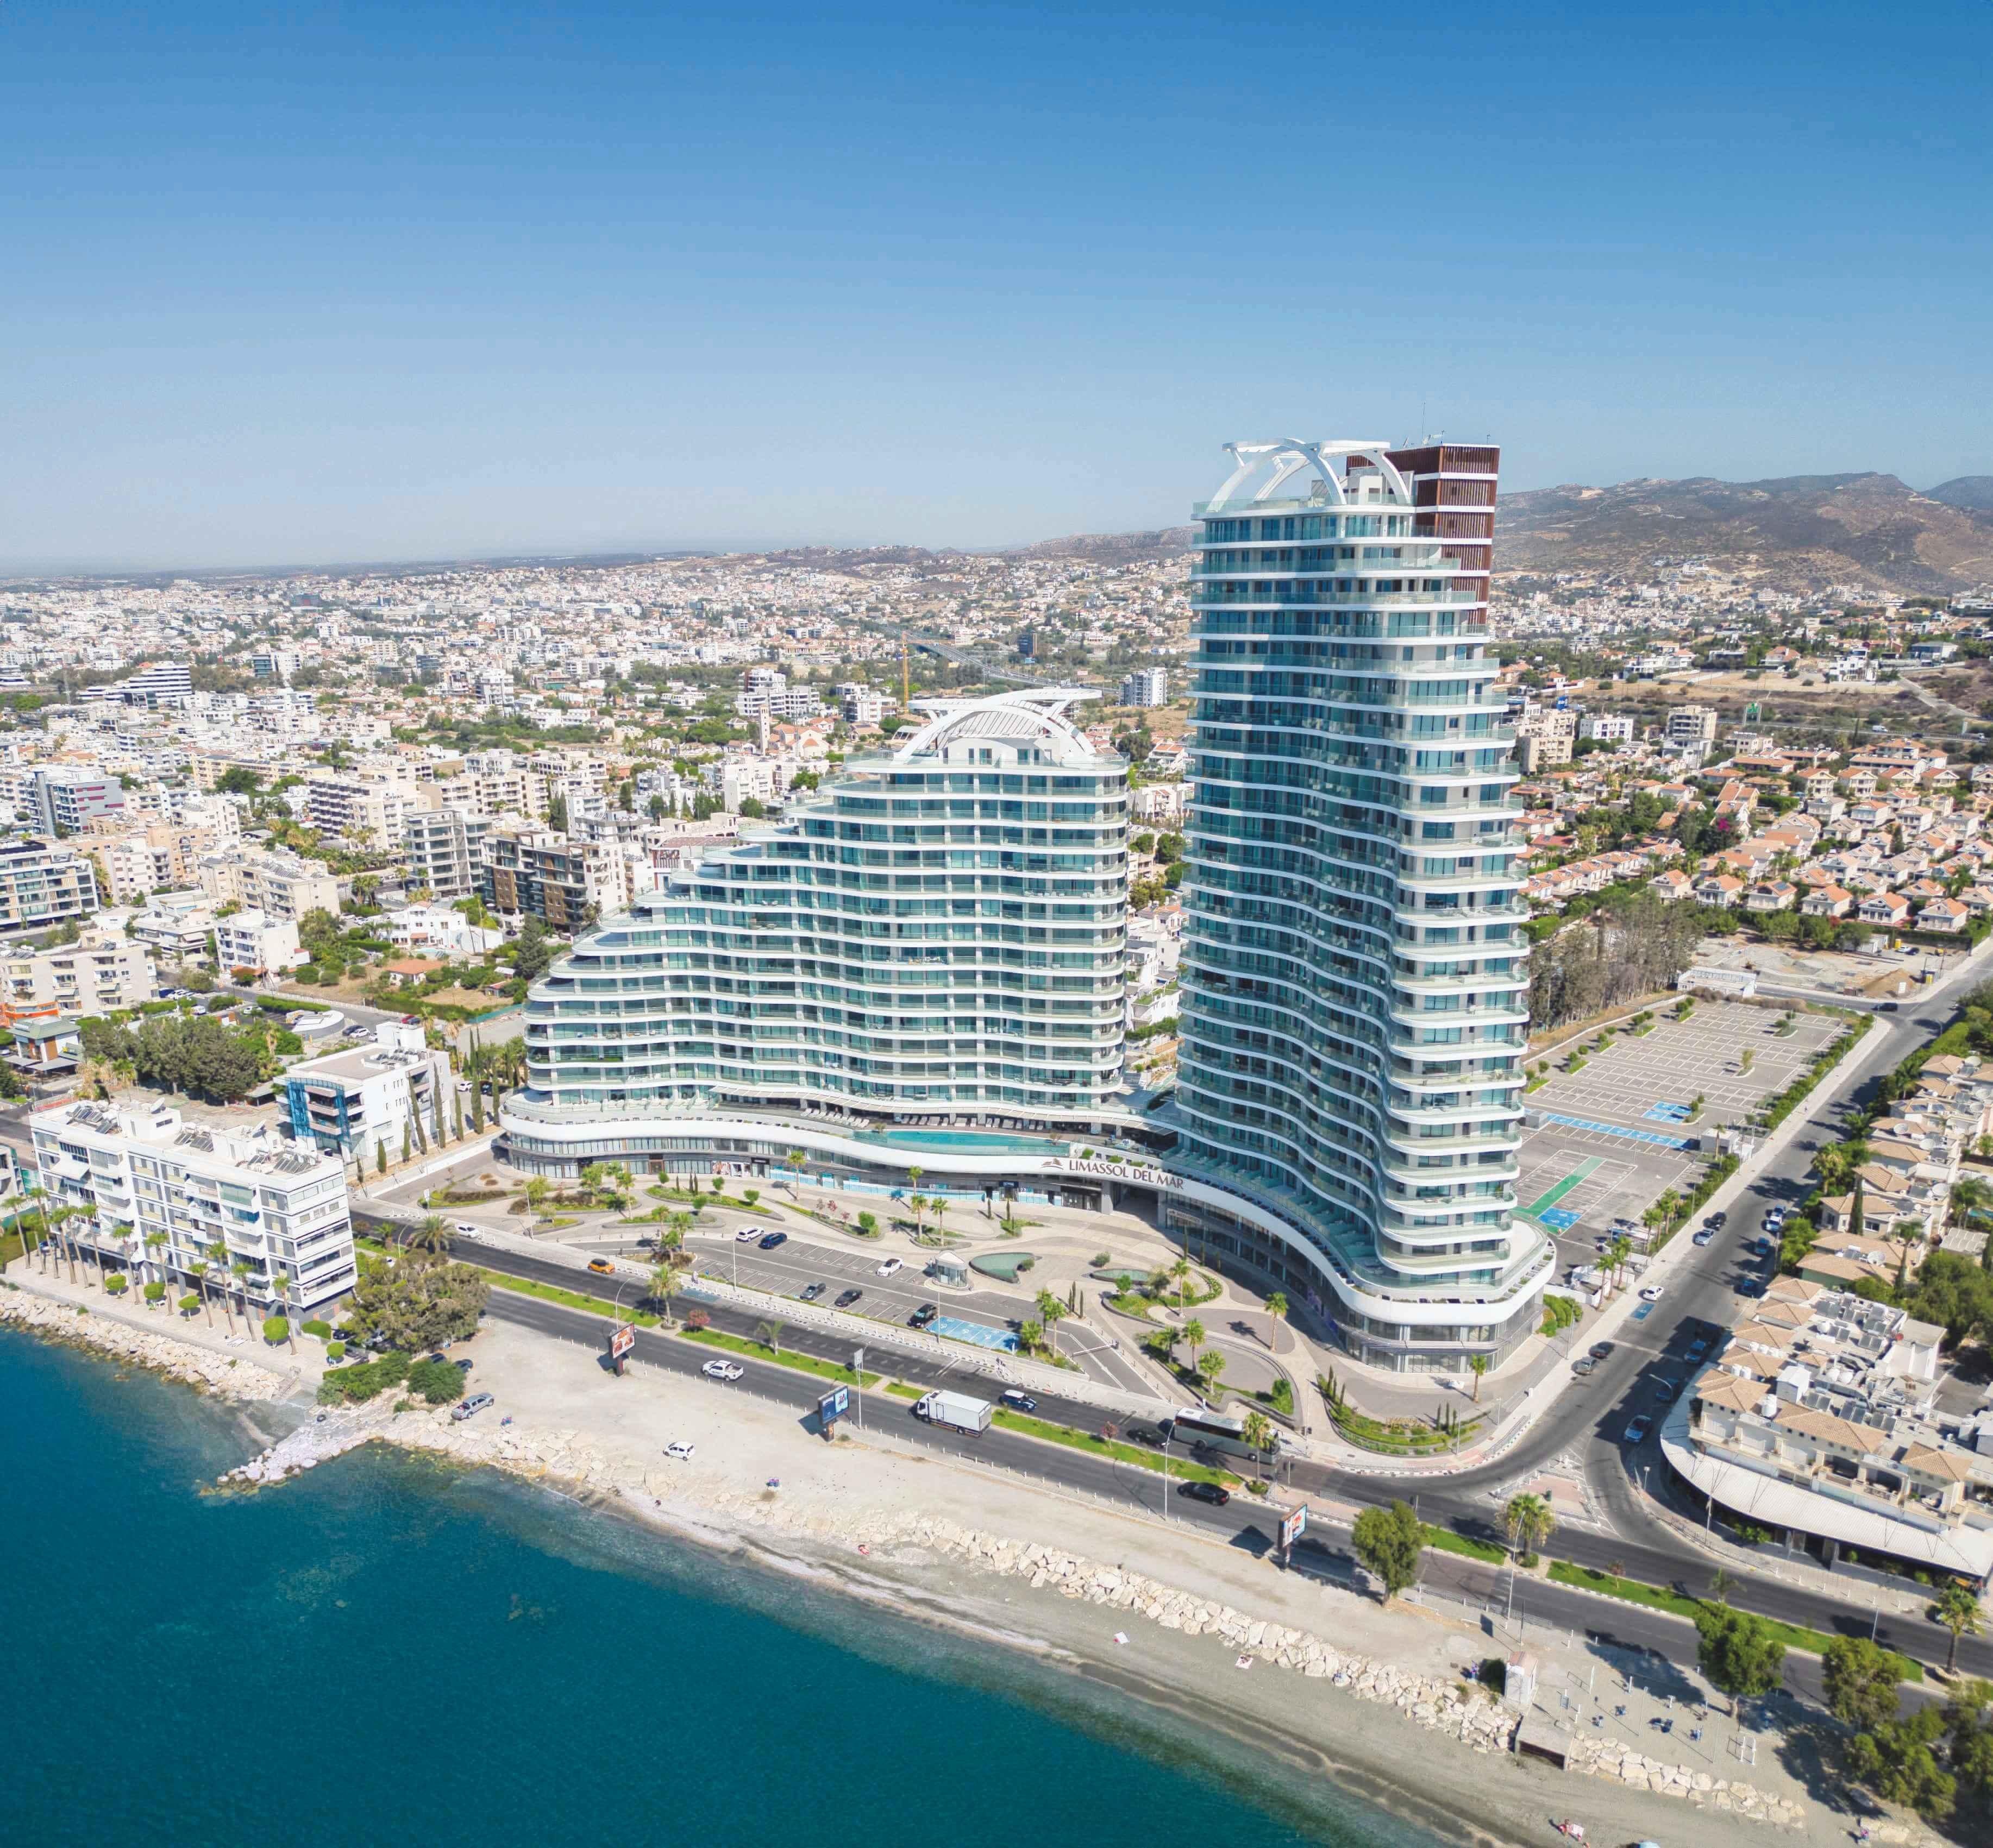
Cyprus is an established destination for entrepreneurs, investors and internationally mobile professionals.
Its tax framework combines a relatively accessible tax-residency system with favorable treatment for certain individuals who qualify as non-domiciled residents.
Under the 60-day rule, an individual may qualify as a Cyprus tax resident after spending at least 60 days in the country during the tax year, provided the other statutory conditions are met. These include maintaining a permanent residence in Cyprus and having qualifying business, employment or directorship connections.
Qualifying non-domiciled residents can benefit from exemptions from Special Defense Contribution on dividends and interest.
Why consider Cyprus?
- ✓EU membership and access to European markets.
- ✓The 60-day tax-residency route for qualifying individuals.
- ✓Attractive treatment of dividends and interest for qualifying non-domiciled residents.
- ✓English widely used in business and professional services.
- ✓Established international company and investment structures.
Cyprus is particularly relevant to business owners and investors whose wealth is generated through international companies and investment portfolios.
Italy
€300,000 Flat Tax for New Residents
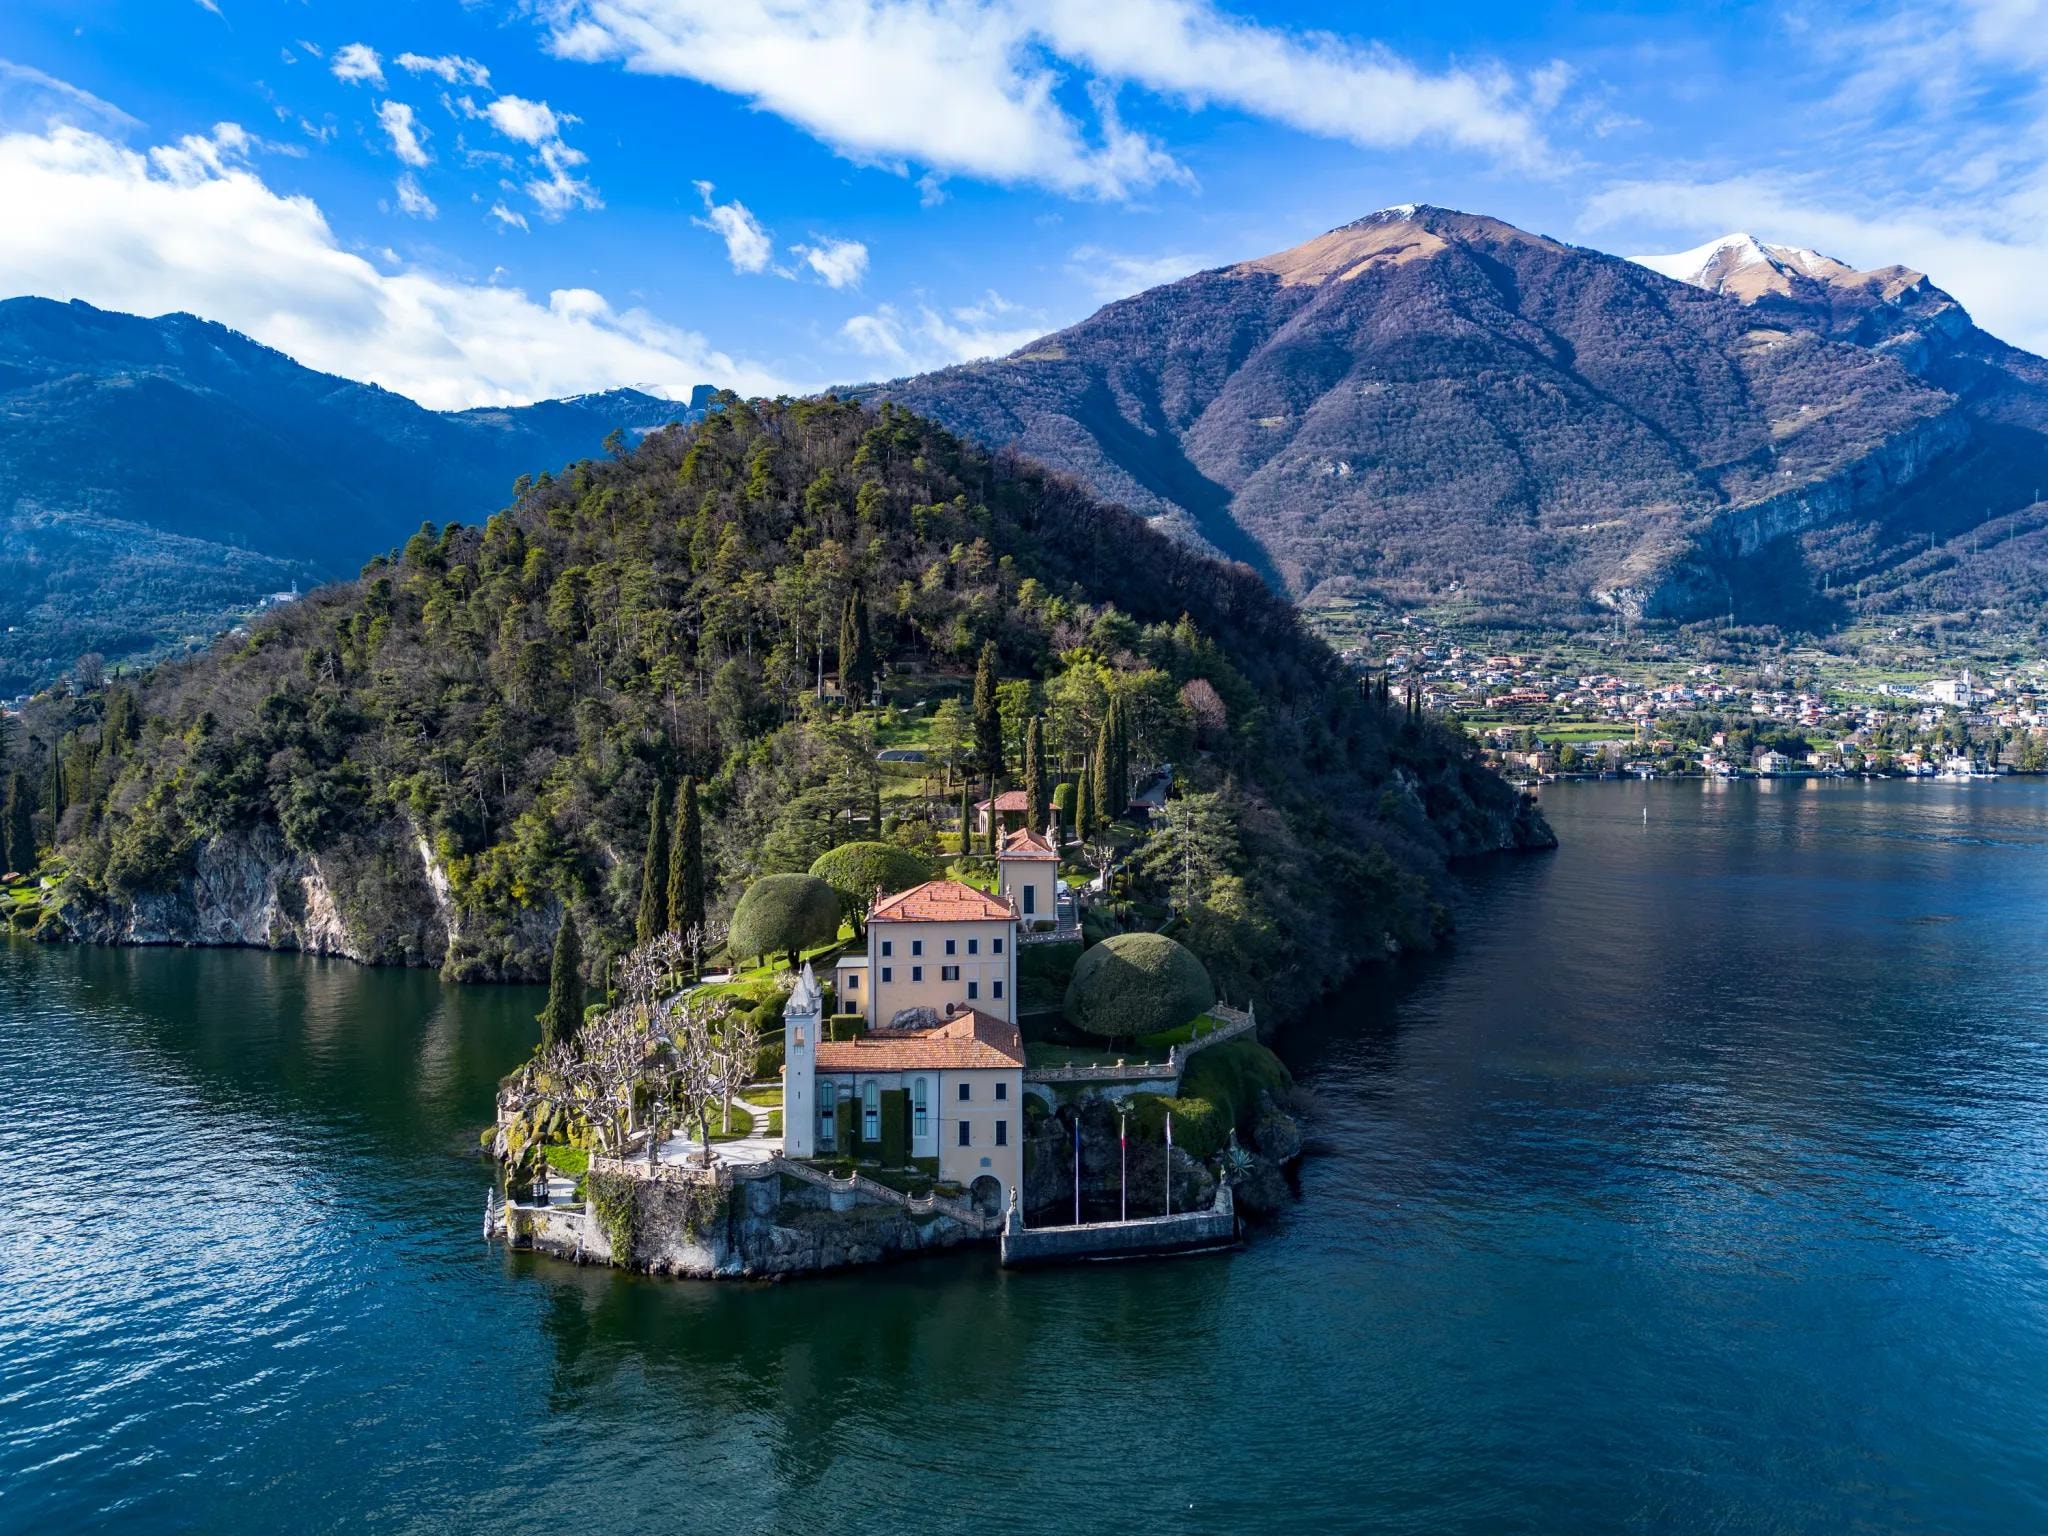
Italy offers one of Europe's most distinctive tax arrangements for high-net-worth individuals relocating their tax residence.
Its special regime allows qualifying new residents to pay a fixed annual substitute tax covering eligible foreign-source income, rather than applying ordinary Italian income tax to that income.
For individuals transferring their tax residence from 2026 onwards, the annual amount is €300,000. Qualifying family members may be included at an additional €50,000 per person.
Eligibility generally requires that the applicant has not been an Italian tax resident for at least nine of the preceding ten tax years. The regime can be used for a maximum of 15 years.
Why consider Italy?
- ✓A predictable annual tax cost for qualifying foreign income.
- ✓Access to the European Union and a major international economy.
- ✓Strong lifestyle appeal, healthcare and education.
- ✓Established business, finance and luxury property markets.
- ✓A regime designed specifically to attract internationally wealthy individuals.
Italy is particularly suitable for individuals with substantial foreign-source income who genuinely intend to establish a life in the country.
Greece
Special Tax Regime for Investors
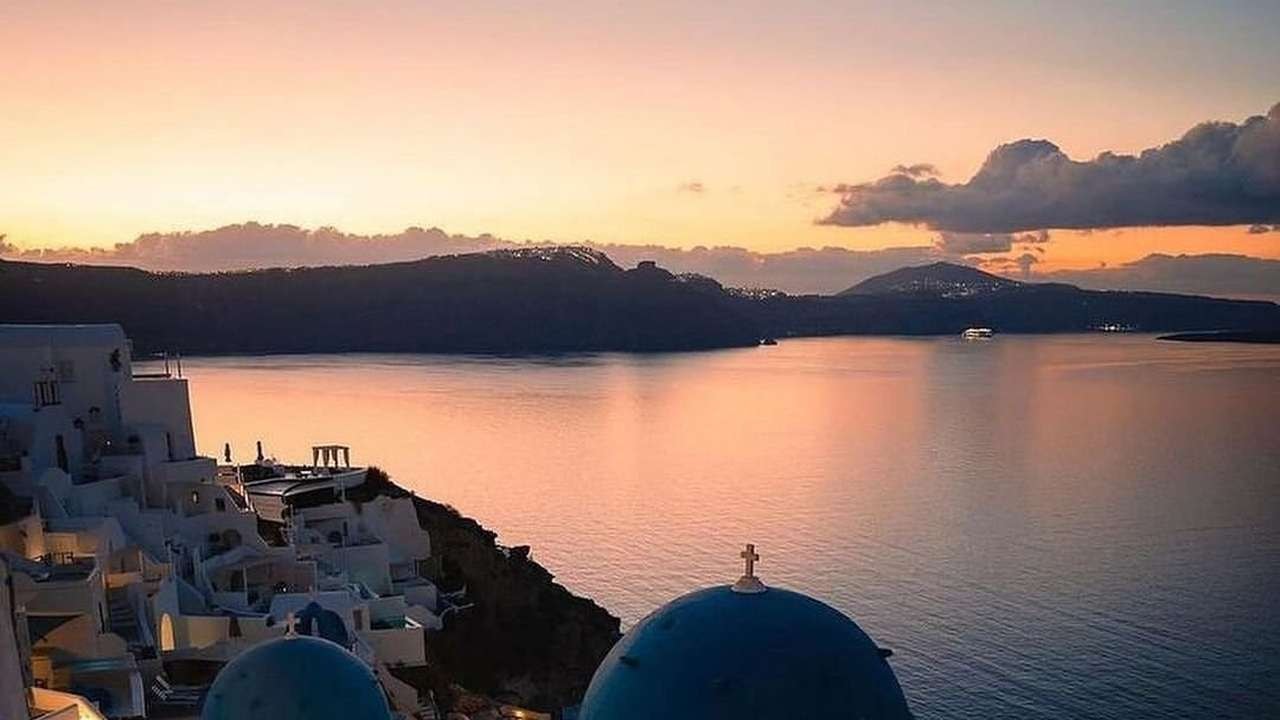
Greece offers an alternative taxation regime for qualifying high-net-worth individuals transferring their tax residence from abroad.
Under Article 5A, eligible applicants can elect to pay an annual lump-sum tax of €100,000 on their foreign-source income, irrespective of the amount of that income. An additional €20,000 applies for each qualifying family member included in the regime.
The regime can apply for up to 15 tax years, subject to eligibility and compliance requirements. Applicants must generally demonstrate that they were not Greek tax residents for seven of the preceding eight years and make a qualifying investment of at least €500,000 in Greece within the prescribed period.
Why consider Greece?
- ✓A fixed annual tax arrangement for qualifying foreign income.
- ✓Mediterranean lifestyle and international connectivity.
- ✓EU membership.
- ✓Investment opportunities in real estate and businesses.
- ✓Options for family relocation and long-term residence.
Greece may appeal to wealthy individuals who want to combine a Mediterranean lifestyle with a structured tax arrangement and a meaningful investment in the country.
Explore Greece residency options →United Arab Emirates
A Low-Tax International Business Base
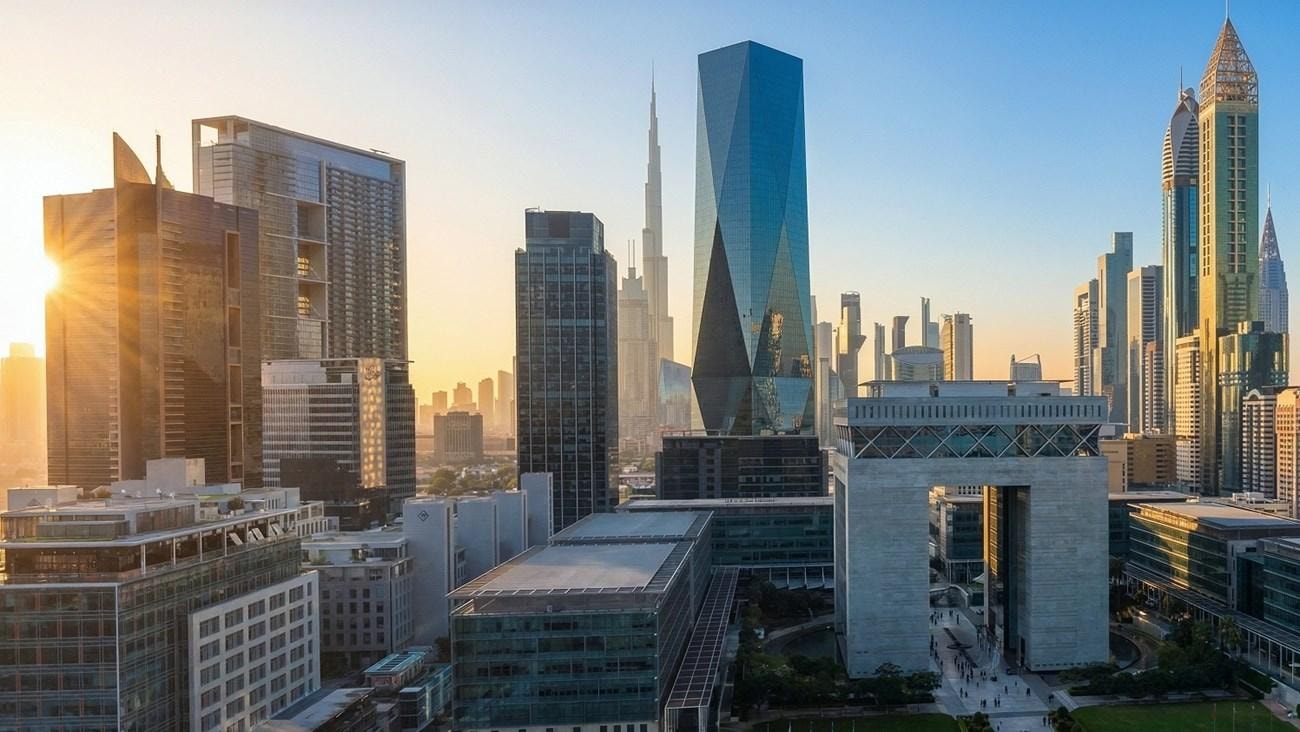
The UAE continues to attract entrepreneurs, investors, executives and internationally mobile families.
The country does not currently impose personal income tax on individuals. This makes it particularly attractive for those earning salaries, receiving investment income or managing international business interests, subject to the applicable rules governing the source and character of income.
However, the UAE's corporate tax system must be considered separately. A 9% corporate tax rate generally applies to taxable business profits exceeding AED 375,000, subject to the relevant exemptions and rules.
Tax residency is not simply a matter of obtaining a Golden Visa or spending a few days in the country. Depending on the circumstances, individuals may qualify through 183 days of physical presence, 90 days combined with additional conditions, or their primary residence and center of financial and personal interests.
Why consider United Arab Emirates?
- ✓No personal income tax under the current system.
- ✓International business and financial infrastructure.
- ✓Attractive residency options, including the Golden Visa.
- ✓Strong connectivity between Europe, Asia and Africa.
- ✓A substantial international expatriate community.
The UAE is especially attractive to entrepreneurs and investors seeking a business-oriented international base outside Europe.
Explore United Arab Emirates residency options →Singapore
Tax Residency and Foreign Income
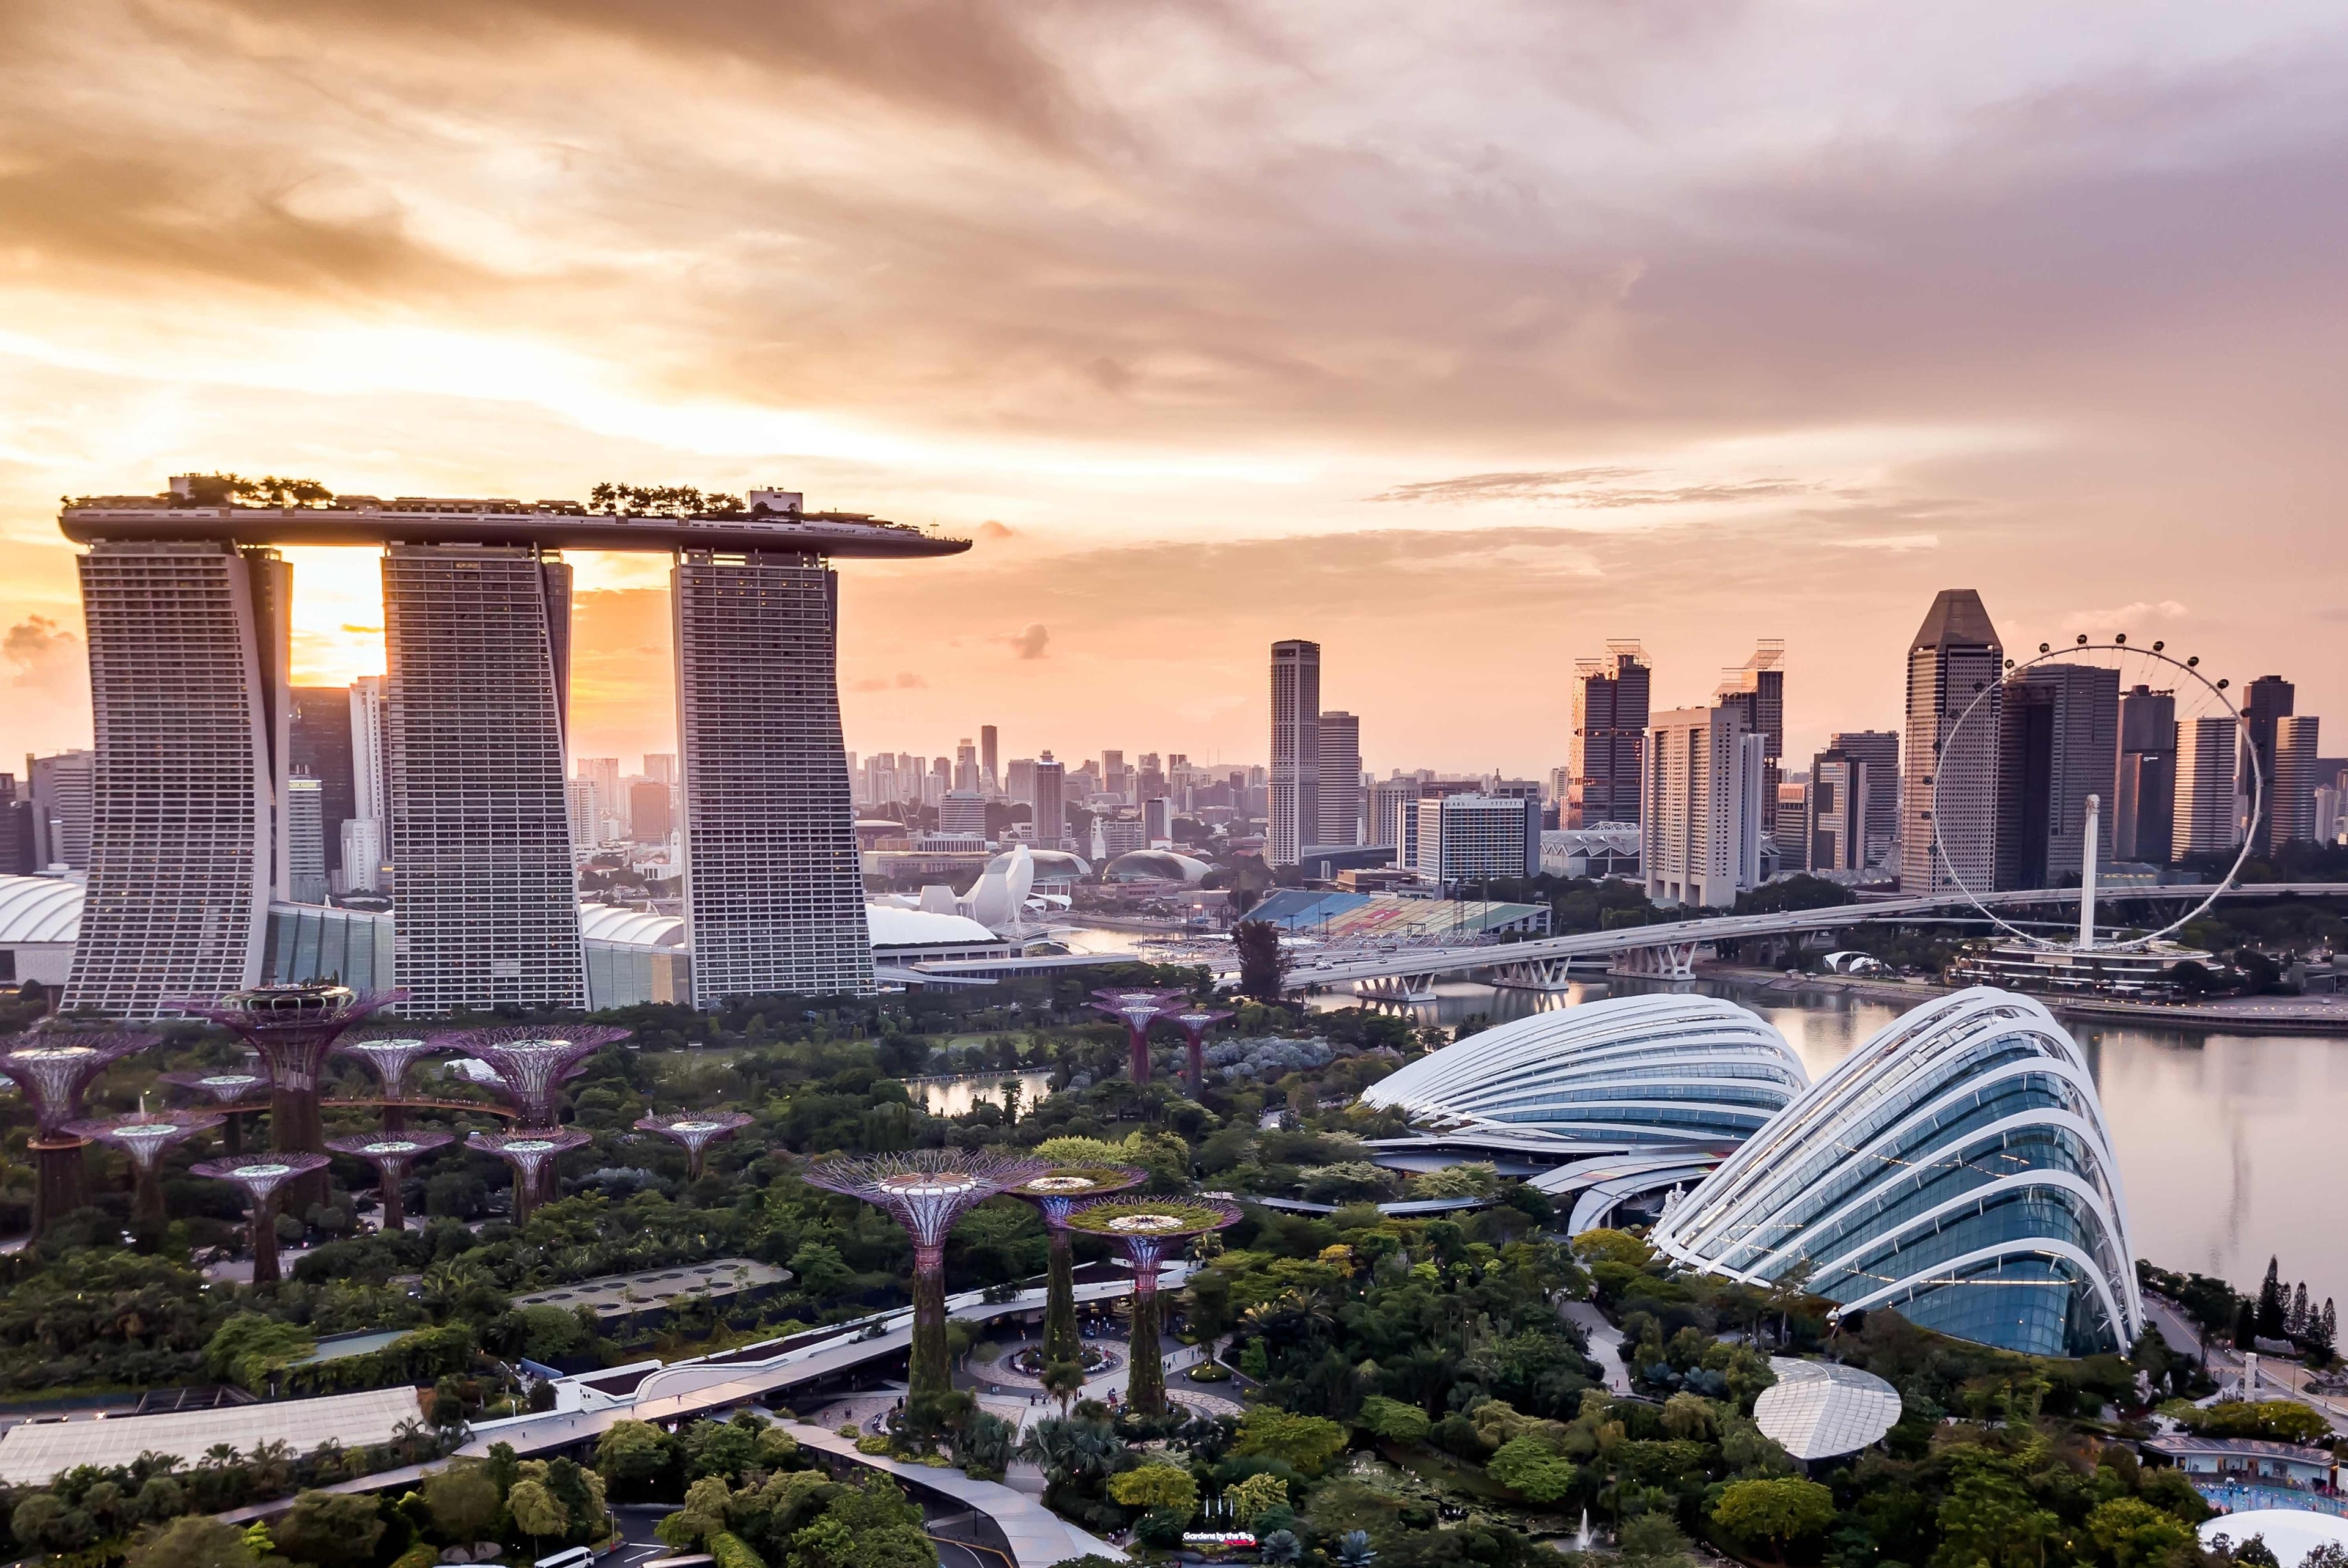
Singapore is a leading destination for internationally mobile entrepreneurs, investors and family offices.
Unlike some low-tax jurisdictions, Singapore does impose personal income tax. Resident individuals are subject to progressive rates, currently reaching 24%.
However, Singapore generally exempts foreign-sourced income received by individual tax residents, subject to specific exceptions. Income earned in Singapore is taxable under the applicable rules.
Singapore's appeal therefore extends beyond headline tax rates. It offers a sophisticated financial services sector, predictable institutions, excellent infrastructure and access to major Asian markets.
Why consider Singapore?
- ✓Political and institutional stability.
- ✓Strong international banking and wealth-management sector.
- ✓Access to Asian business markets.
- ✓Established family-office ecosystem.
- ✓Favorable treatment of qualifying foreign-source income.
Singapore is particularly relevant for entrepreneurs, investors and families whose business and investment interests are concentrated in Asia.
Panama
Territorial Taxation
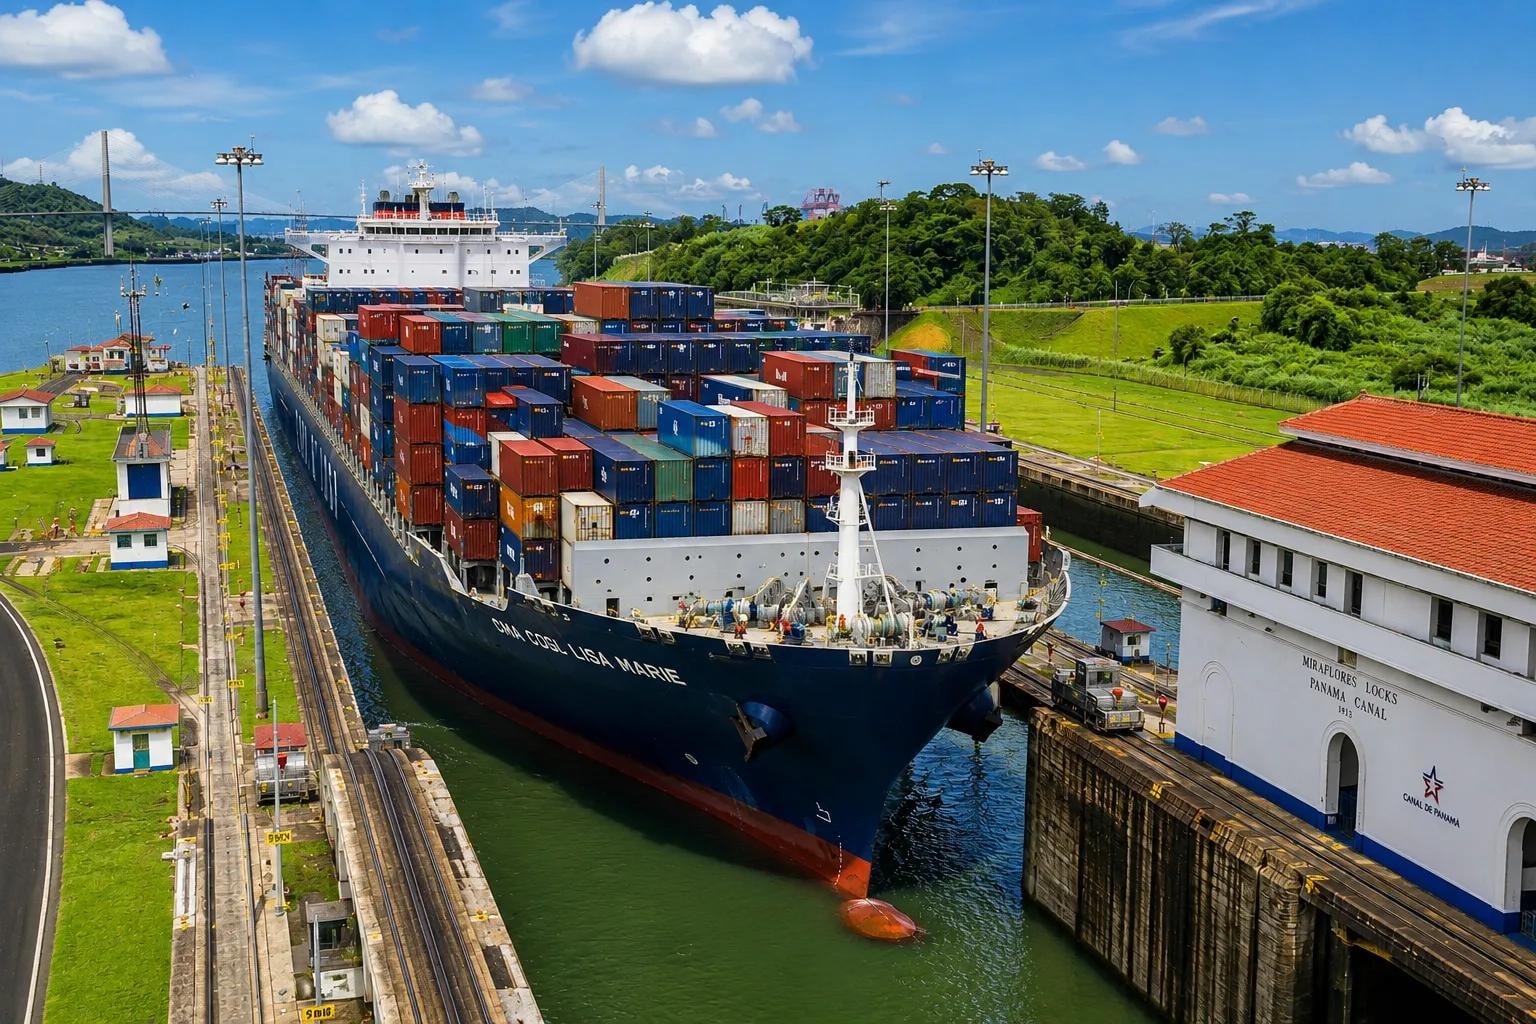
Panama offers a different proposition based on the territorial principle of taxation.
In general, income generated from foreign sources is not subject to Panamanian income tax, while income derived from Panamanian sources is taxable under the applicable domestic rules.
This can make Panama attractive to internationally mobile individuals whose income is generated outside the country.
The country also offers several immigration routes, including investment-related and other residence categories, depending on nationality and eligibility.
Why consider Panama?
- ✓Territorial taxation of income.
- ✓Use of the US dollar as legal tender.
- ✓Established international banking and business connections.
- ✓Geographic proximity to North and South America.
- ✓Several residence options for foreign nationals.
Panama may be attractive to individuals seeking a Latin American base, although careful analysis of income sourcing and international reporting obligations is essential.
Explore Panama residency options →Monaco
Tax Residency for Wealthy Individuals
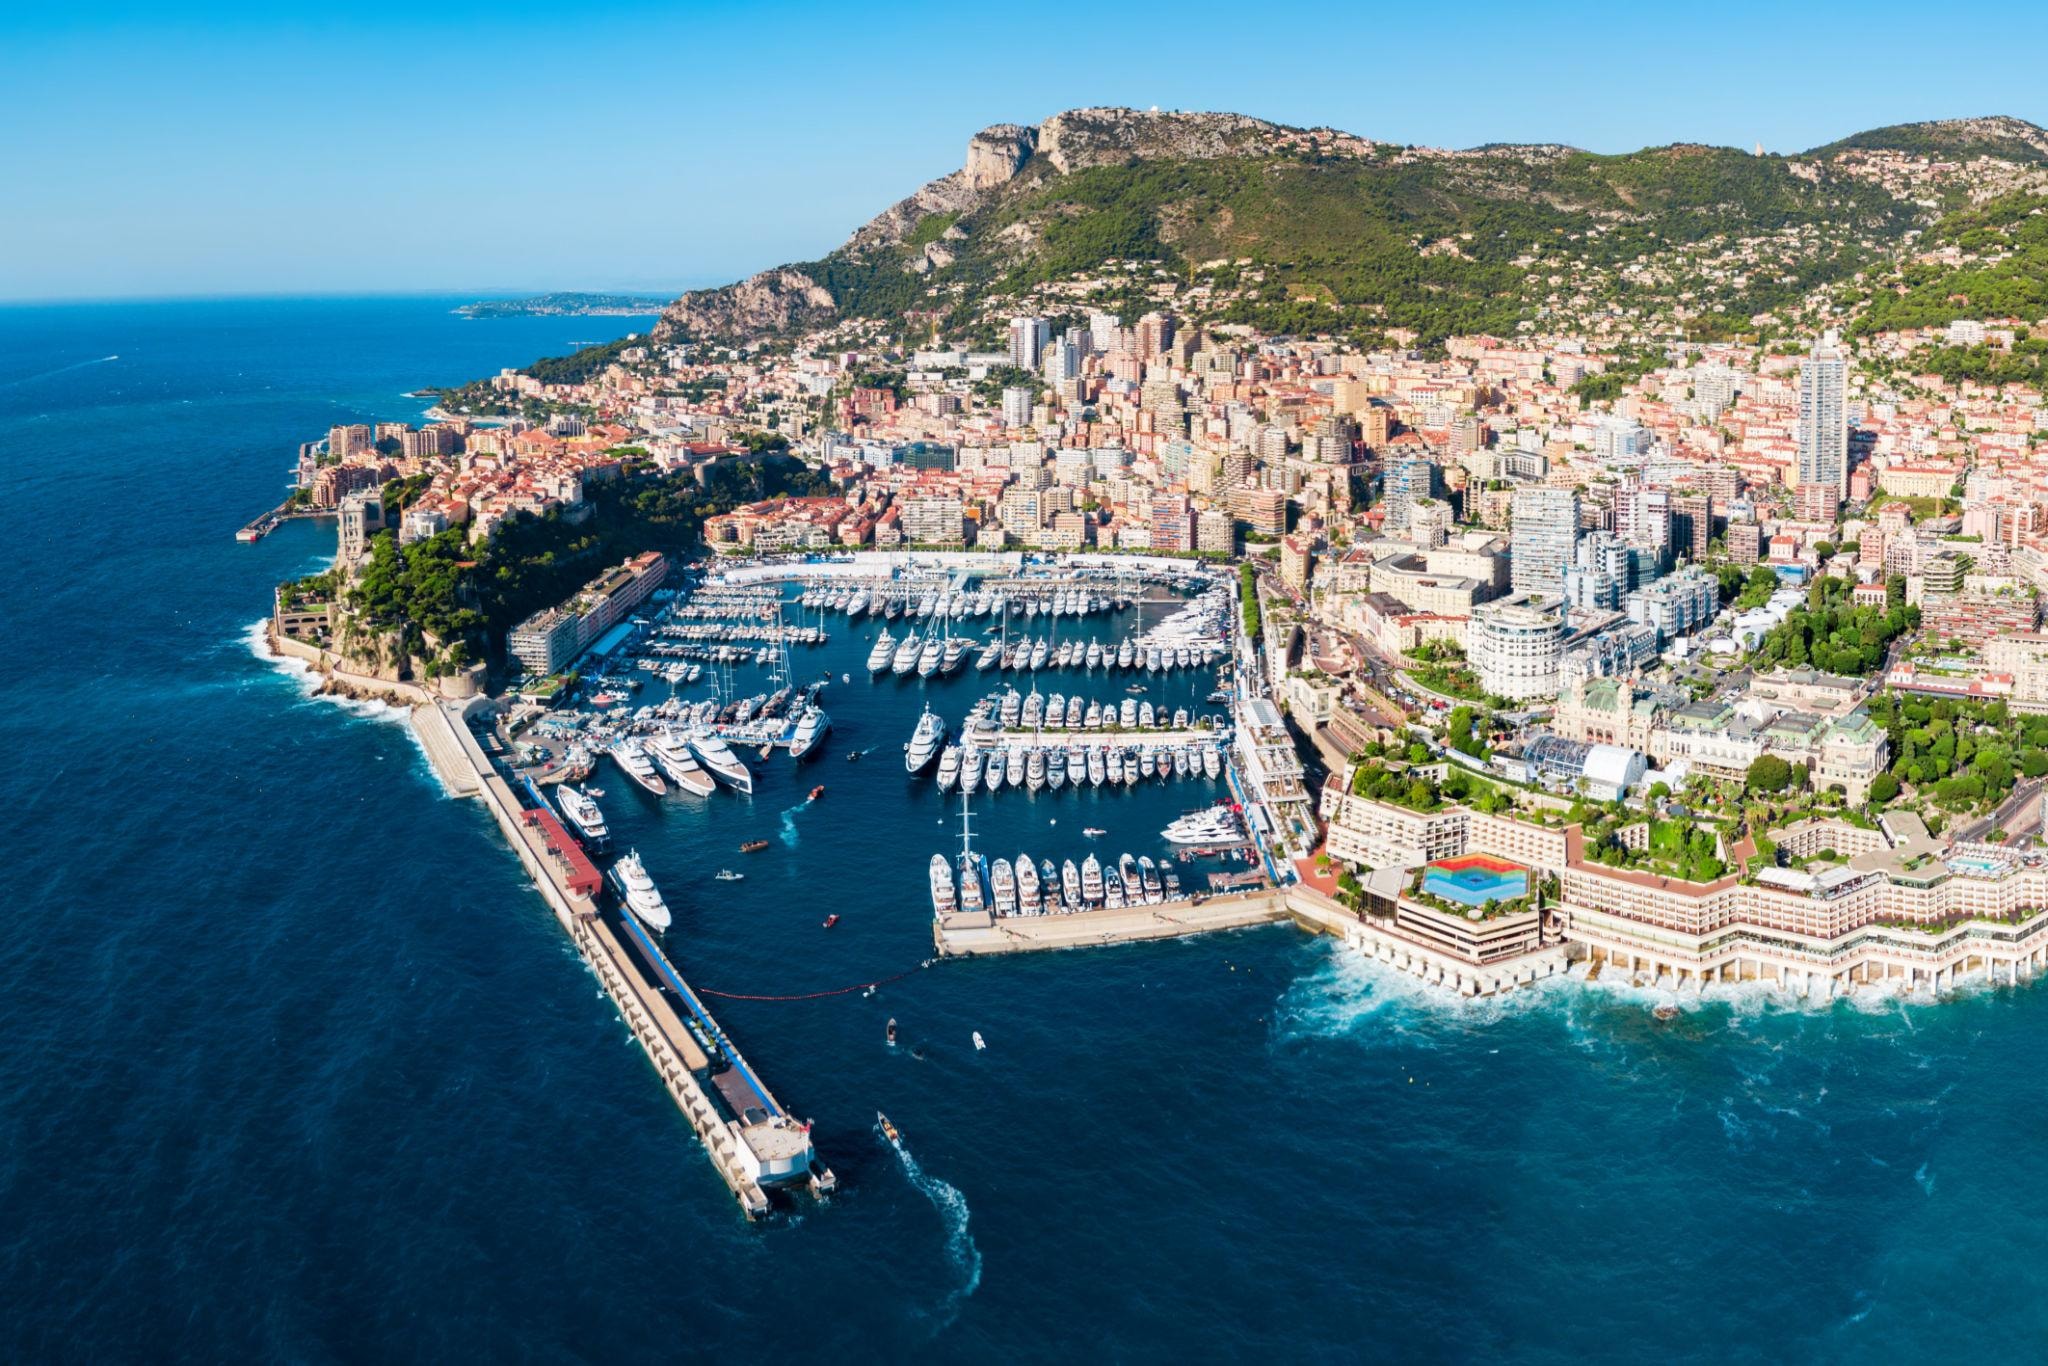
Monaco remains one of the world's most recognized destinations for wealthy individuals seeking a European residence with no general personal income tax.
Residents generally do not pay personal income tax, although French nationals are subject to specific exceptions under the France–Monaco tax arrangements.
Monaco's appeal is supported by its location on the Mediterranean, security, infrastructure, established luxury property market and proximity to major European financial centers.
However, establishing residence requires more than obtaining an address. Applicants must demonstrate suitable accommodation and sufficient financial resources, and must genuinely establish their residence in accordance with the applicable requirements.
Why consider Monaco?
- ✓No general personal income tax for most residents.
- ✓Established international wealth-management environment.
- ✓High levels of security and infrastructure.
- ✓European location and Mediterranean lifestyle.
- ✓Proximity to France and other major European markets.
Monaco is particularly relevant to ultra-high-net-worth individuals who can meet its substantial accommodation and financial requirements.
Switzerland
Lump-Sum Taxation
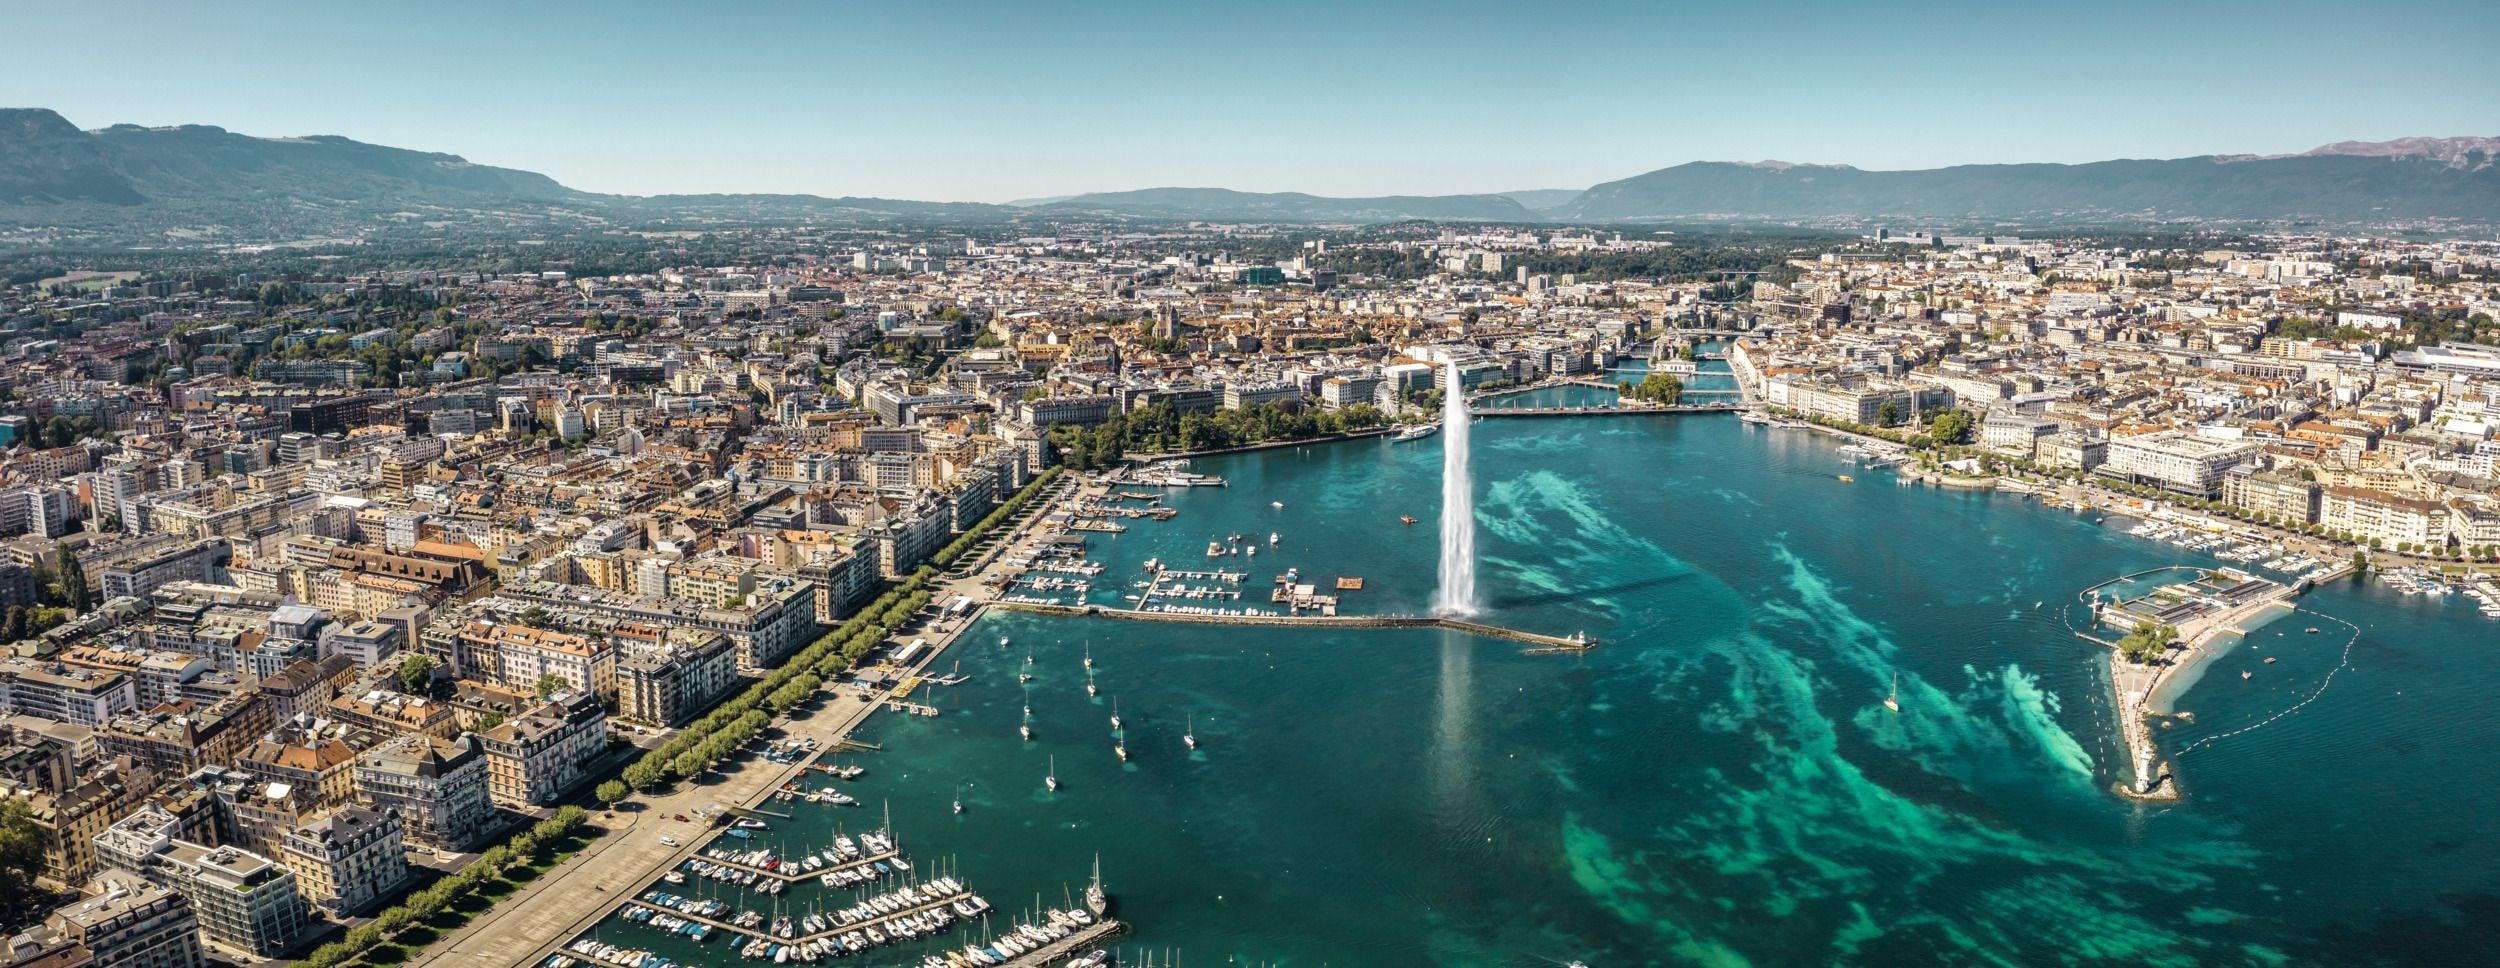
Switzerland offers a distinctive option for certain foreign nationals through its expenditure-based taxation system, commonly known as lump-sum taxation.
Eligible foreign nationals who establish residence in Switzerland and do not undertake gainful employment there may qualify for taxation based on their living expenditure rather than their worldwide income and assets in the ordinary way.
The system is implemented differently across cantons, and the applicable tax calculation and minimum taxable base can vary.
Switzerland's attraction goes well beyond taxation. Its political stability, legal system, financial services sector, healthcare, education and infrastructure make it a leading destination for wealthy international families.
Why consider Switzerland?
- ✓Political and economic stability.
- ✓Established private banking and wealth-management industry.
- ✓High-quality healthcare and education.
- ✓Access to European markets.
- ✓Expenditure-based taxation for qualifying foreign nationals in participating cantons.
Switzerland is particularly relevant to wealthy individuals who prioritize institutional stability and quality of life and are prepared to meet the financial and residence requirements.
Bulgaria
Europe's Competitive Flat-Tax Destination
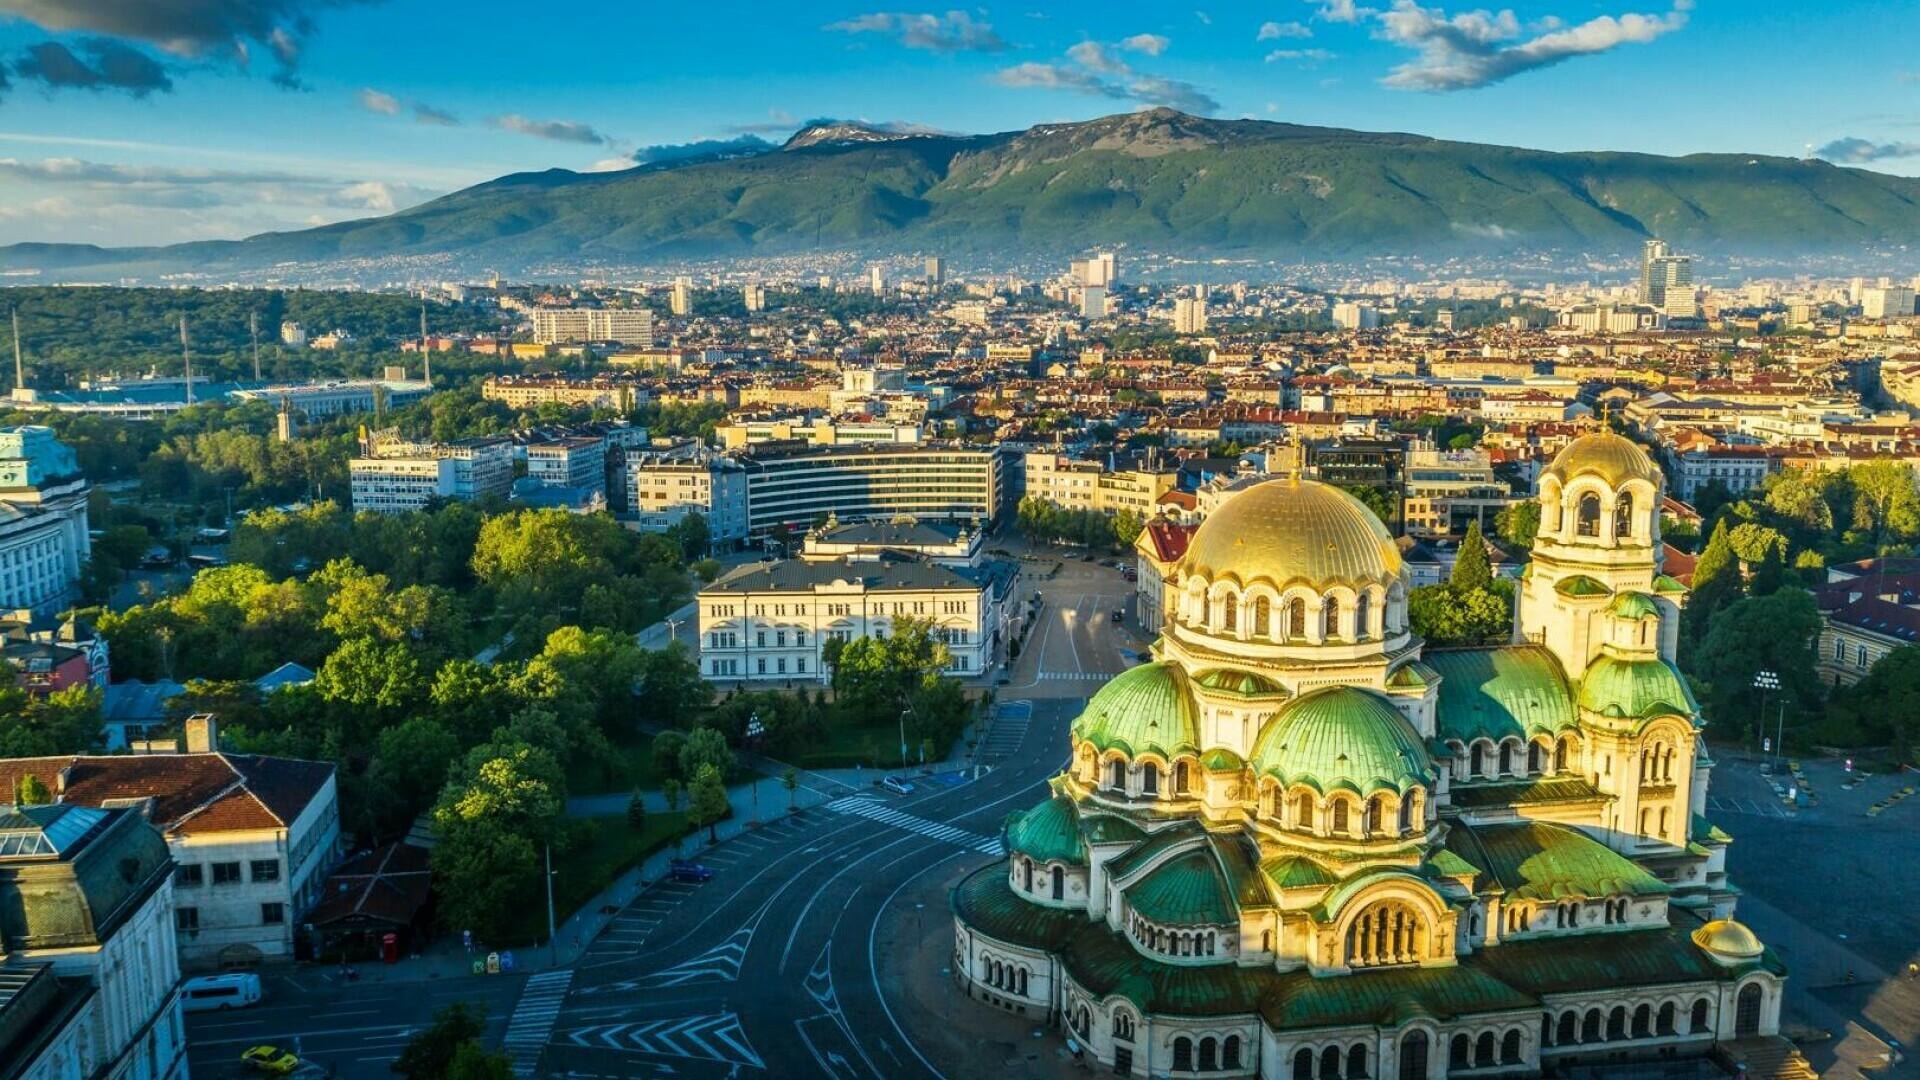
Bulgaria offers one of the most competitive tax systems in the European Union, combining a flat 10% personal income tax with a 10% corporate income tax. Dividends distributed to individuals are generally subject to a further 5% tax.
Unlike several European countries that rely on special tax arrangements to attract wealthy foreign residents, Bulgaria applies a relatively straightforward tax framework to residents generally. This makes it particularly interesting for entrepreneurs, business owners, investors and internationally mobile professionals seeking a lower-tax European base.
Bulgarian tax residents are generally subject to taxation on their worldwide income. Tax residency can arise through maintaining a permanent address in Bulgaria, spending more than 183 days in the country during a 12-month period, or having one's center of vital interests there. A permanent address alone does not necessarily establish tax residency where the individual's center of vital interests is elsewhere.
Bulgaria's appeal extends beyond taxation. As an EU member state, it offers access to the European single market, an established business environment, relatively affordable living costs and connections to both European and regional markets.
Why consider Bulgaria?
- ✓Flat 10% personal income tax rate on most taxable personal income.
- ✓10% corporate income tax rate.
- ✓5% tax on dividends distributed to individuals.
- ✓EU membership and access to the European single market.
- ✓Relatively affordable property, living and business operating costs.
- ✓Attractive environment for entrepreneurs, company owners and international professionals.
Bulgaria is particularly relevant to individuals who want to establish a genuine European residence while benefiting from relatively low and predictable taxation. It can be especially attractive to business owners and investors whose financial structures make use of its competitive personal and corporate tax framework. Social security contributions, income classification and applicable international tax treaties should also be considered when assessing the overall tax position.
Explore Bulgaria residency options →Uruguay
South American Stability and an 11-Year Tax Holiday for New Residents
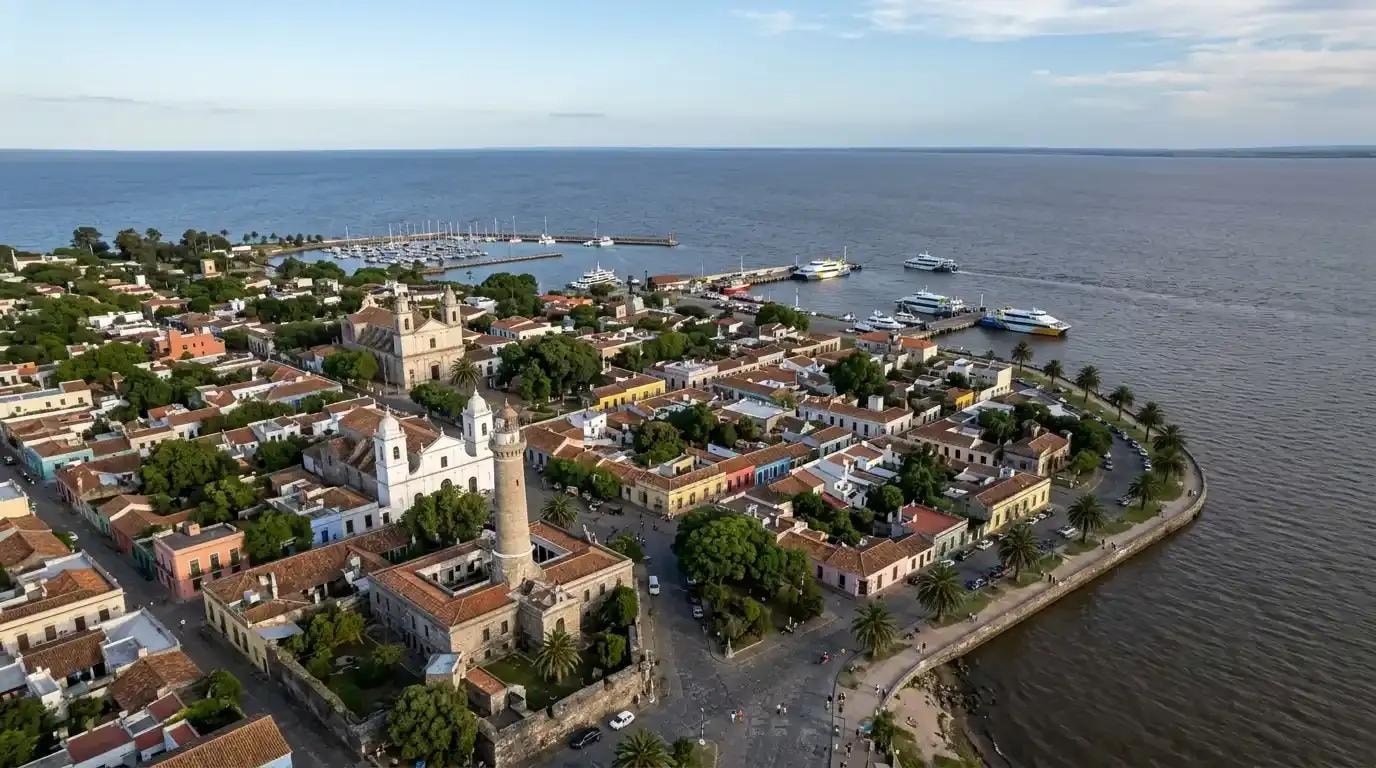
Uruguay is increasingly recognized as an attractive destination for internationally mobile investors and wealthy families seeking a stable South American base. Its established institutions, comparatively high standard of living and historically territorial approach to taxation have long distinguished it from many other countries in the region.
An important development took effect on 1 January 2026, introducing an updated preferential tax regime for qualifying new tax residents. Under the new impatriate regime, eligible individuals can elect to be taxed under Uruguay's non-resident income tax system (IRNR) on specified foreign-source capital income and capital gains for the year in which they establish tax residency and the following ten tax years.
The regime covers qualifying investment income, including interest and dividends from foreign entities, as well as certain foreign-source rental income and capital gains from the disposal of assets located abroad. These qualifying foreign-source amounts are generally outside the scope of IRNR, providing an effective tax holiday for the covered income during the qualifying period.
To qualify, individuals must generally not have been Uruguayan tax residents during the two immediately preceding tax years and must not have previously used an incompatible tax-holiday arrangement. They must also satisfy one of the applicable qualifying conditions — spending more than 183 days in Uruguay during the calendar year, or meeting specified investment requirements including real estate investments exceeding 12.5 million Indexed Units or annual contributions of at least 625,000 Indexed Units to qualifying investment funds.
Why consider Uruguay?
- ✓An 11-year preferential tax regime for qualifying new tax residents (from 1 January 2026).
- ✓Favorable treatment of specified foreign-source investment income and capital gains.
- ✓Established democratic institutions and a comparatively stable political and economic environment.
- ✓Attractive lifestyle, particularly in Montevideo and the coastal resort destination of Punta del Este.
- ✓Access to South American markets and regional business opportunities.
- ✓Established professional services, banking and investment infrastructure.
Uruguay is particularly relevant to investors, entrepreneurs and internationally mobile families seeking a long-term base in South America. Its preferential regime can be especially attractive to individuals with substantial international investment portfolios, dividend income and foreign assets who are prepared to meet the residency and qualifying conditions. The 2026 reforms make careful advance tax planning particularly important.
Explore Uruguay residency options →Comparing the Best Tax Residency Countries
Side-by-Side Overview
| Country | Personal income tax | Special tax regime | Tax residency requirements |
|---|---|---|---|
| Malta | Standard rate 35%; 15% on qualifying foreign income remitted under special programs | Individual Tax Program — €35,000 minimum annual tax (from 2027) | Qualifying property (purchase €700,000+ or rent €14,000+/yr); no gainful employment in Malta |
| Cyprus | Progressive up to 35%; non-dom exemptions on qualifying dividends and interest | Non-domicile status; 60-day tax residency route | 60 days in Cyprus; permanent residence; qualifying business/employment connection; not tax resident elsewhere |
| Italy | Progressive up to 43%; €300,000 flat annual substitute tax on eligible foreign income | Flat-tax regime for new residents (Art. 24-bis TUIR) | Not Italian tax resident for 9 of preceding 10 years; available for up to 15 years |
| Greece | Progressive up to 44%; €100,000 annual lump-sum tax on foreign income under special regime | Alternative taxation regime (Art. 5A ITC) | Not Greek tax resident for 7 of preceding 8 years; €500,000 qualifying investment in Greece |
| UAE | No personal income tax; 9% corporate tax on business profits above AED 375,000 | No special personal tax regime — territorial system applies | 183 days physical presence; or 90 days with qualifying connections; or primary residence and center of interests |
| Singapore | Progressive up to 24%; qualifying foreign-source income generally exempt | Foreign-source income exemption for tax residents | 183 days physical presence; or employment in Singapore |
| Panama | Progressive up to 25% on Panama-source income; foreign-source income generally exempt | Territorial tax system | Various residency categories; Friendly Nations Visa; Qualified Investor Visa |
| Monaco | No personal income tax for most residents; French nationals subject to France–Monaco treaty | No formal special regime — general absence of personal income tax | Qualifying accommodation; proof of financial resources; genuine residence establishment |
| Switzerland | Progressive (federal + cantonal); lump-sum taxation available for qualifying foreign nationals | Expenditure-based (lump-sum) taxation — canton-dependent | No gainful employment in Switzerland; qualifying expenditure base; canton-specific minimum tax |
| Bulgaria | Flat 10% on most personal income; 5% dividend tax | No special new-resident regime — flat rate applies generally | Permanent address, more than 183 days in a 12-month period, or center of vital interests |
| Uruguay | Progressive 10–36% on employment income; qualifying foreign capital income may receive preferential treatment | 11-year IRNR option for qualifying new residents (from 1 January 2026) | More than 183 days or other statutory residency criteria, with additional investment conditions for the preferential regime |
Sources: Malta CFR; Cyprus Tax Department; Italian Revenue Agency; Greek IAPR; UAE Ministry of Finance; IRAS Singapore; Panama DGI; Monaco Direction des Services Fiscaux; Swiss Federal Tax Administration; Bulgarian National Revenue Agency; Uruguay DGI. For general guidance only — verify current rules with qualified advisers.
Considering a Change of Tax Residency?
Choosing a new country of residence involves more than comparing headline tax rates. Immigration eligibility, investment requirements, family circumstances and existing tax obligations all matter. JPA World helps internationally mobile individuals and families explore residency options and coordinate their international mobility planning.
Tax Residency vs Immigration Residency
A Critical Distinction
One of the most common misunderstandings in international mobility planning is the assumption that obtaining a residence permit automatically changes an individual's tax position.
It does not.
Immigration residency gives an individual the legal right to live in a country. Tax residency determines where that individual is considered liable to tax under the relevant domestic rules and international agreements.
A person may hold permanent residence in one country while remaining tax resident elsewhere. Similarly, obtaining a second residence permit does not necessarily terminate existing tax obligations.
The number of days spent in a country is important, but it is not always the only consideration. Authorities may also examine:
- —Where the individual maintains their principal home.
- —Where their spouse and dependent children live.
- —Where their business and economic interests are located.
- —Where their personal and social connections are strongest.
- —Whether they have genuinely ceased to be resident in their former country.
For this reason, international relocation should be planned as a coordinated immigration and tax exercise.
Special Considerations for US Citizens
Green Card Holders Too
For Americans considering a second residence or relocation abroad, the tax analysis is particularly important. The United States taxes its citizens on worldwide income regardless of where they live — a rule that applies to no other major developed country except Eritrea.
Obtaining tax residency in Malta, Cyprus, the UAE or any other jurisdiction does not eliminate US federal tax obligations. US citizens remain required to file US tax returns and report worldwide income even while living abroad.
Worldwide income taxation
US citizens and long-term green card holders are generally subject to US federal income tax on their worldwide income, regardless of where they reside or where the income is earned.
Foreign Tax Credit (FTC)
A credit may be available for foreign income taxes paid on income that is also subject to US tax. This can reduce double taxation in practice, but the rules are complex and the credit does not apply in all situations.
Foreign Earned Income Exclusion (FEIE)
Qualifying US citizens living abroad may exclude a portion of their foreign earned income from US taxable income. For 2026, the exclusion is $130,000. It applies only to earned income (wages, self-employment) and not to investment income, dividends or capital gains.
FBAR and FATCA reporting
US citizens with foreign financial accounts exceeding $10,000 at any point during the year must file an FBAR (FinCEN Form 114). FATCA (Foreign Account Tax Compliance Act) requires additional reporting of foreign financial assets on Form 8938. Non-compliance can result in substantial penalties.
Exit tax considerations
US citizens who relinquish citizenship and long-term permanent residents who terminate their status may be subject to an exit tax under IRC Section 877A if they meet certain net worth or tax liability thresholds. This can result in a deemed sale of worldwide assets at fair market value on the date of expatriation.
This makes specialist US tax advice essential before any decision to relocate, obtain a second citizenship, or change immigration status.
Related Reading
Tax and Compliance Questions for U.S. Families Considering a Plan B
Before pursuing a second citizenship or foreign residency, U.S. families need to understand how tax obligations, foreign account reporting, and compliance requirements actually work.
Read the article →Frequently Asked Questions
Tax Residency Essentials
There is no single best country for everyone. The UAE, Malta, Cyprus, Italy, Greece, Monaco and Switzerland offer different tax arrangements. The most suitable destination depends on the individual's income sources, assets, nationality, family circumstances and willingness to relocate.
The UAE and Monaco are among the best-known jurisdictions without general personal income tax for individuals, although Monaco has an important exception for certain French nationals. Other taxes, reporting obligations and business taxation may still apply.
Yes, in certain jurisdictions. Cyprus offers a 60-day tax-residency route subject to additional conditions. The UAE also has qualifying routes based on 90 days of physical presence and other requirements. Each country's rules must be assessed individually.
No. An immigration residence permit provides the legal right to reside in a country but does not automatically establish tax residency. Separate tax-residency criteria apply.
Generally, no. US citizens remain subject to US taxation on worldwide income regardless of where they live. Certain exclusions and foreign tax credits may be available, but specialist advice is essential.
Malta retains its 15% rate on qualifying foreign-source income remitted to the country. However, its Individual Tax Program introduces a €35,000 minimum annual tax for Global Resident Status and higher qualifying property requirements from 1 January 2027.
Bulgaria applies a flat 10% personal income tax rate on most taxable income and a 10% corporate income tax rate. Dividends distributed to individuals are generally subject to a further 5% tax. There is no special new-resident regime — the flat rate applies to residents generally. This makes Bulgaria particularly interesting for entrepreneurs, business owners and internationally mobile professionals who want a straightforward, low-tax European base within the EU.
From 1 January 2026, qualifying new tax residents in Uruguay can elect to be taxed under Uruguay's non-resident income tax system (IRNR) on specified foreign-source capital income and capital gains for the year of establishing tax residency and the following ten years. The regime covers qualifying investment income including interest, dividends from foreign entities, certain foreign-source rental income and capital gains from assets located abroad. To qualify, individuals must generally not have been Uruguayan tax residents during the two preceding tax years and must satisfy residency or investment conditions. The preferential regime is conditional — it does not apply automatically to everyone who moves to Uruguay.
Tax residency determines where an individual is treated as resident for tax purposes. Citizenship establishes nationality and may carry additional legal and tax consequences. The two statuses are not interchangeable.
Explore Our Country Residency Programs
Global Mobility Destinations


DISCLAIMER: This page is for general educational and informational purposes only and does not constitute legal, tax, financial or investment advice. Tax legislation and residency requirements may change. The arrangements described are subject to individual eligibility, statutory conditions and applicable anti-avoidance provisions. Readers should obtain independent professional tax and legal advice in both their current and proposed countries of residence before making decisions.